Nigeria: Economic Recovery Will Open New Business Opportunities
folder_open Business Outlook , West Africa
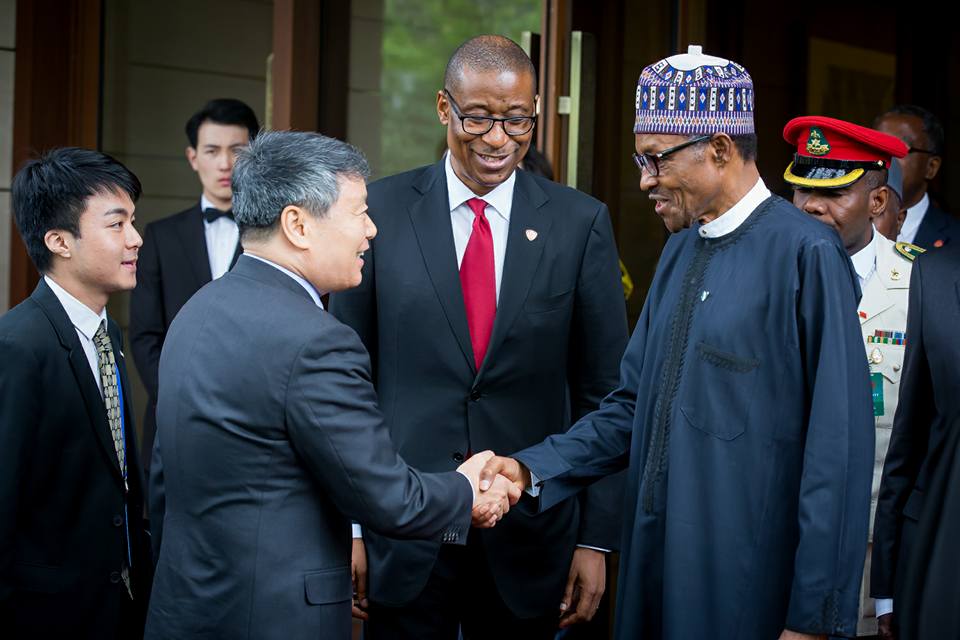
New economic measures adopted by the recently re-elected government of Muhammadu Buhari will try to expand Nigeria's economy away from oil income dependence and focus on consolidating Nigeria's manufacturing base – thereby opening new business opportunities for overseas suppliers and investors. Nigeria's population and gross domestic product is projected to reach 399 million people and cross $3.3 trillion by 2050. However, much needs to be done to bridge the gap between the reality of Africa’s largest economy and its undisputed potential. While Nigeria’s economy has performed much better in recent years than it did during previous boom-bust oil-price cycles, such as in the late 1970s or mid-1980s, oil prices continue to dominate the country’s growth pattern. Nigeria emerged from recession in 2017, with a growth rate of 0.8%, driven mainly by the oil sector. Growth was higher in 2018 (at 1.9%) and more broad-based; however, it still fell below the population growth rate, government projections and pre-recession levels. As Africa’s top oil producer, Nigeria is heavily reliant on crude, with the fuel accounting for 90 percent of foreign-currency earnings and two-thirds of government income. Without reforms to reduce its dependence on oil income, Nigeria risks “a lost decade” of flat economic growth. The country has recently held national elections in 2019, for the sixth consecutive time since its return to democracy in 1999. The incumbent president, Muhammadu Buhari won the elections and would be sworn in for a second term on May 29, 2019. Robust Economic Growth Nigeria’s economy grew in 2018 at its fastest pace since a recession two years earlier. Nigeria’s central bank expects the economy to pick up in 2019, forecasting a gross domestic product growth of 3 percent, up from 1.9 percent recorded last year. On the other hand, Nigeria continues to face massive developmental challenges, which include the need to reduce the dependency on oil and diversify the economy, address insufficient infrastructure, and build strong and effective institutions, as well as governance issues and public financial management systems. Nigeria accounts for nearly 20% of continental GDP and about 75% of the West Africa economy. Despite this dominance, its exports to rest of Africa are estimated at 12.7%, and only 3.7% of total trade is within the Economic Community of West African States. Nigeria has yet to ratify the Continental Free Trade Agreement, pending the outcome of broad consultations with captains of industry and other stakeholders. Large pockets of Nigeria’s population still live in poverty, without adequate access to basic services, and could benefit from more inclusive development policies. The lack of job opportunities is at the core of the high poverty levels, of regional inequality, and of social and political unrest in the country. Economic growth has been recovering since the third quarter of 2016, when the recession bottomed out. Higher oil prices helped Nigeria exit that contraction. Low oil prices will slow down growth in 2019, but the longer-term outlook depends heavily on how the government tackles the expansion of country's economy away from oil income. The World Bank had expected growth to be slightly less than 2 percent in 2019 as the elections kept foreign investors away. New Beginnings To its credit, the Nigerian government has secured the territorial integrity of the nation by reclaiming territory in the Northeast and has tackled big-ticket corruption, introducing and improving transparency and accountability in the management of public funds. Nigeria also committed to unprecedented investments to start and finish critical infrastructure projects in power, roads, and rail across the country, as well as direct investments in people to lift them up—the largest social investment program in Africa. Nigeria accounts for about 47% of West Africa’s population, and has one of the largest populations of youth in the world.
Africa: Ripe for Business: Export to Africa and Reap the Benefits
folder_open Articles , Business Outlook
Currently, 6 of the world’s 10 fastest growing economies are in Africa, and the ease of doing business in Africa is improving to the extent that a good number of countries (including South Africa, Ghana, Mauritius and Tunisia) now outperform China, India, Brazil and Russia. In addition, FDI inflows to Africa have demonstrated year-to-year growth since 2010 and now amount to US$ 50 billion. The key reasons behind this growth surge included government action to end armed conflicts, improve macroeconomic conditions, and undertake microeconomic reforms to create a better business climate. To start, several African countries halted their deadly hostilities, creating the political stability necessary to restart economic growth. Next, Africa’s economies grew healthier as governments reduced the average inflation rate from 22 per cent in the 1990s to 8 per cent after 2000. They trimmed their foreign debt by one-quarter and shrunk their budget deficits by two-thirds. Finally, African governments increasingly adopted policies to energize markets. They privatised state-owned enterprises, increased the openness of trade, lowered corporate taxes, strengthened regulatory and legal systems, and provided critical physical and social infrastructure. Nigeria privatized more than 116 enterprises between 1999 and 2006, for example, and Morocco and Egypt struck free-trade agreements with major export partners. Although the policies of many governments have a long way to go, these important first steps enabled a private business sector to emerge. Together, such structural changes helped fuel an African productivity revolution by helping companies to achieve greater economies of scale, increase investment, and become more competitive. After declining through the 1980s and 1990s, the continent’s productivity started growing again in 2000, averaging 2.7 percent since that year. These productivity gains occurred across countries and sectors. This growth acceleration has started to improve conditions for Africa’s people by reducing the poverty rate. But several measures of health and education have not improved as fast. To lift living standards more broadly, the continent must sustain or increase its recent pace of economic growth. To be sure, Africa has benefited from the surge in commodity prices over the past decade. Oil rose from less than $20 a barrel in 1999 to more than $145 in 2008. Prices for minerals, grain, and other raw materials also soared on rising global demand. Political change in Africa is rapidly happening in unexpected pockets. Observers are actively monitoring situations in certain countries, in particular South Africa, Ethiopia, and Zimbabwe, with an excitement for future socio-political change that could follow these headwinds. Yet all consideration of the current political movements suggest that the imagined economic change is not necessarily an easy sequel to the political prologue. Political change is also sweeping across the African contient: Ethiopia The unexpected (or expected, depending on who you ask) resignation of Ethiopian Prime Minister Hailemariam Desalegn, in theory, paves the way for change. But many insiders are not exactly sure what path will be chosen by the ruling Ethiopian People’s Revolutionary Democratic Front. Faced with ongoing demonstrations that began sporadically in 2015, the ruling party has two options in front of it: Choose someone open to allowing increased political freedom or Appoint a party hardliner to shut down the dissent. For many political analysts, the arrival of Desalegn’s resignation day is an odd juxtaposition with the rising economic prowess of the country. Ethiopia, as it goes, always craftily kept political freedom and economic growth in two separate buckets of discussion, especially as the growth justified the political environment in which it excelled. But the death of the pervasive and endearing prime minister Meles Zenawi in 2012 opened the door for a discussion on politics in conjunction with economic transition, theoretically blurring the line that separated the two subjects in public discourse. The economics of the country could possibly have to account for its internal politics. Yields on Ethiopia’s $1 billion 2024 Eurobonds fell a few basis points after the government announced a state of emergency following the prime minister’s resignation. That drop was not significant enough to stir major concern amongst investors in the country. But investors will watch closely to see how the next few months play out. Two things are increasingly truer today than yesterday: (1) Ethiopians think protests can affect political change and the stance of the country’s political leaders, and (2) markets and investors have punished other countries for instability (ask Kenya in late 2017 and South Africa for the last two years). Zimbabwe The death of Zimbabwe opposition leader Morgan Tsvangirai quickly followed the exit of former President Robert Mugabe. With no clear leader to fill the power vacuum in the opposing Movement for Democratic Change (MDC) party, the ruling ZANU-PF may face little opposition in a presidential election expected before July this year. Tsvangirai won, at least, in the first round of the vote in 2008, but eventually lost a disputed election to Mugabe and later formed a unity government with him. Some opposition leaders are suggesting that the death of Tsvangirai may encourage President Emmerson Mnangagwa to ensure the Zimbabwe election stays on track with timing. That positive, in the eyes of political critics, is not too positive if a true debate on the economy and the general direction of Zimbabwe cannot be had without a face or voice to put opposite President Mnangagwe. The reuniting of Tsvangirai last year with his former allies, Welshman Ncube and Tendai Biti, who both left Tsvangirai’s wing of the party, to run together in the 2019 elections was a boost to the opposition’s spirits in the midst of flailing motivation and energy in the anti-Mugabe camp. Yet now the question becomes whether the former allies can push forward in Tsvangirai’s memory and Mugabe’s absence. No one truly knows where the allegiances may fall. Some observers suggest that ZANU-PF is not a tight-knit as advertised. Even if true, ZANU-PF has proven its ability to win national elections. Regardless, the economics in the country require change. Zimbabweans need infrastructure, an economic rebound, and jobs among other things. But who has the new ideas and energy in 2018 to endure a long process in rejuvenating the economic spirits of businesses and locals? Investors and markets – excited to have a serious discussion on Zimbabwe again – want to reward the country for political change. Yet the question may still be whether Zimbabwe cares about what outsiders are saying or what the market is selling it. South Africa The rise to the presidency for Cyril Ramaphosa in the immediate aftermath of the resignation from South African President Jacob Zuma spells opportunity for the challenged country. Investors, markets, and pundits alike have punished Africa’s most developed economy for Zuma’s leadership and rule. It only follows that the stark opposite leader – admired in the business community for his successes and once pursued by the beloved Nelson Mandela to be his deputy president – should spell relief for investors and potentially have a Trump-esque bump on markets in the early days. Yet the ‘dawn of a new day’ in South Africa may require more than a simple change of leadership. The South African mining sector requires wage and ownership changes as well as tax changes to spur more investment and strengthen a buried gem (no pun intended) in the country. The economy requires a solution to energy troubles. The state-owned power company Eskom remains a trouble spot for the country with regards to its poor balance sheet performance. And the country needs jobs to combat unemployment and boost consumer spending as nearly every consumer and retail-based related sub-sector complains that South Africans cannot afford to spend despite their usual appetite for doing so. Beyond the economics and the politics, President Ramaphosa will have to battle pockets of nationalism within the country that want to restrict land rights, fight back against privatization, and avoid the dirty fights to reform certain government institutions, such as the South African Revenue Service. At the end of the day, political change and the arrival of President Ramaphosa may be a breath of fresh air, but the ruling party cannot inhale too long with too much on its plate to do and with an impending general election. A few early reforms may be the difference between winning and losing for the ruling ANC in early 2019. The message to any company or investor still not in Africa is that today is the day that business in Africa is made and it might already be too late tomorrow. Africa is the now, no longer the future. Any CEO who has not presented his or her board of directors with their Africa strategy needs to get to work on such a plan and implement the plan as soon as possible in order to reap the benefits by gaining first entry into the emerging markets in Africa. The Africa train has already left the station. You are either on it or you risk becoming irrelevant.
Kenya Aims To Boost Meat Exports
folder_open Business Outlook , East Africa
Kenya plans to boost its meat exports by investing in state-of-the-art slaughterhouses that meet international quality standards. This was announced by none other than President Uhuru at a recent meeting with government officials and business owners recently. “We will begin with the export of live animals but in two years, we should have our own export slaughterhouse. My vision is to revive this important sector,” said President Uhuru Kenyatta. Meat exports to Europe and the Middle East markets has been growing in recent years and the building of halal-certified slaughterhouses will certainly boost Kenya’s foreign exchange earnings though meat exports. “My main interest is that the farmer and herder of livestock get good prices for their animals,” said the President. President Kenyatta said livestock farming used to be a lucrative agribusiness in the 1970s but was brought down through mismanagement. “We used to do well in this livestock industry in the early 1970s. Unfortunately, due to mismanagement, it collapsed,” he said. Global Foods and Blue Mountain are two UAE-based companies that have been appointed to market Kenya Meat Commission (KMC) products in the Middle East with Dubai as the distribution point. KMC is also planning to set up distribution centres and cold storage warehouses in the Kuwait, Qatar, Saudi Arabia, the Democratic Republic of Congo (DRC), Sudan, and Egypt. “We want to directly take charge of the export market by doing away with middle men in our supply chain system. This will also help us convert agent commission fees into income,” said Patrick Mutemi, the deputy managing commissioner and head of finance and marketing at KMC. The Middle East is a prime market for small stock products — lamb, mutton, and goat meat — while corned beef is more popular in the African market and Saudi Arabia. Recently, a team from the United Arab Emirates visited Kenya to assess the capacity of Kenya Meat Commission to export meat to the Middle East country. The inspectors, mainly veterinary doctors, nutritionists and environmentalists studied how KMC meets international standards on food safety, health and sanitation, livestock disease control and meat handling. KMC is targeting the Middle East market to increase revenues and the company targets a 20 per cent profit at the end of this financial year. To enhance its capacity in meeting the market demand, KMC is constructing six satellite abattoirs in major livestock keeping areas countrywide, including Wajir, Samburu, Kajiado, Isiolo, Mandera, Garissa, Marsabit and Turkana counties. The European Union had banned the importation of Kenyan beef due to food safety concerns as a result of livestock diseases.
How to Export to African Countries
folder_open Articles , Business Outlook
In times of economic meltdown, planning which markets of the world to target for exports, the continent of Africa doesn’t always come top of the list. In fact, rarely. Part of that is down to preconceived opinions about the continent. Constant images of war and starvation don’t always make a business believe there are riches to be earned from business dealings on the continent. However the truth is that the economic situation in Africa is changing: Africa hosts the majority of the top ten fastest growing countries in the world. The IMF estimates that economic growth in sub-Saharan Africa will be over 5.5% in 2019. The World Bank believes that most African countries will reach “middle income” (at least US$1000 per person a year) by 2025 if current growth rates continue. Nearly half of the labour force in Africa is expected to have some secondary-level education by 2020. Africa has around 98 million people with household incomes exceeding $5,000 meaning they can direct more than half of their income towards discretionary spending. It’s expected that this figure will reach 128 million by 2020. All of a sudden exporting to Africa looks a much rosier prospects than in the past and already countries such as the US, Brazil, China and India have increased their business dealings with the continent. The UK and South African Governments set targets to double bilateral trade in the next five years. The main imported commodities are: Machinery and equipment Chemicals Petroleum products Scientific instruments Foodstuffs Tyres & Batteries Automobile Spare Parts Cosmetics Stationery Items Household Electronics While Africa faces tremendous challenges on the road to integration into the world trading system, there is more to Africa's trade performance than meets the eye. Many African export sectors have outperformed world market growth. Champions in the African export portfolio include cut flowers, frozen fish, t-shirts, women's trousers, footwear and transistors. These cases illustrate that Africa can compete. How to Export to Africa In many ways it’s pretty much the same as making plans to start exporting goods to any country in the world. You need to start off by doing some research to find out if your product compares to what is currently being supplied in the target market. Find out who your competitors are and what services they offer as well as their pricing schedules. Look at duty structures, freight rates, currency fluctuations and then you will have a better idea of whether you have a marketable product. There are enormous opportunities in Africa but you have to thoroughly research the market. If your business produces machinery and equipment, chemicals, petroleum products, scientific instruments or foodstuffs then exporting to Africa is a great idea. It’s important to have an agent who can travel to your target market on a regular basis and has established a network of customers there. This allows you to concentrate on supply and production. At some point though it’s important for you to get on that plane and travel to Africa. It’s important to meet people face-to-face and build proper relationships but make sure that you learn about their culture to avoid any potential embarrassing mistakes. Some countries such a Nigeria offer both complimentary and fee-based market research tools to help possible exporters from other countries to analyze the market and gain insight into specific sectors. Other advantages with Africa are lower salaries and rents, improving infrastructures and growth in those who have broadband. There are risks though as in any emerging market. These include crime and corruption. Also in a country such as South Africa you have to respect laws that demand a certain percentage of employees, directors and shareholders are black. In Gabon there are strict rules that have to be adhered to. These protect the health, safety and environment of Gabon’s citizens from sub standard imported goods. Exporters need to provide a Certificate of Conformity for Customs clearance. Since October 2013 this has been compulsory. It’s important to break into a growing market like Africa as early as possible. Make sure you do your research, employ agents to keep a close eye on your investments and make sure you comply with all the relevant laws in the country you are exporting to and exporting to Africa really can pay dividends. Traditionally a commodity exporter, Africa is diversifying into industrial goods and services. Tunisia is a good example of Africa's emerging growth areas. Exports of electronic components have passed the US$ 500 million mark, expanding at annual rates of 22% for several years. In clothing, despite fierce global competition, Tunisia has been able to increase its market share. It now ranks eighth among 184 countries in the Trade Performance Index for clothing, reflecting exports of US$ 2.5 billion to a diversified group of countries. Mauritius, Africa's other major clothing exporter, has also increased its world market share, supplying garments worth US$ 1 billion. In textiles, the continent's leading suppliers are South Africa, Morocco and Zimbabwe. More recently, a number of very successful small companies are driving rapid improvement in textile exports in Cameroon, Madagascar and Sudan. Export Markets in Africa Southern Africa has joined the ranks of the world's leading trading areas. In five out of the 14 sectors covered by the Trade Performance Index, the Southern African Customs Union (SACU) figures among the world's top 15 exporters. Transport equipment is one example, where SACU ranks ninth, with exports of US$ 1.4 billion and a high degree of product and market diversification. South Africa, the largest member of SACU, has experienced growing interest of transnational corporations to invest in the country, as shown by UNCTAD's recent survey on foreign direct investment in Africa. Success stories of African exporters are not confined, as is often perceived, to the Maghreb countries and southern Africa. Exports in sub-Saharan Africa (excluding southern Africa) are far from marginal for some product groups. This region, for instance, is a major net exporter of fresh food and agro-based products. Moreover, several countries are improving their competitiveness in exports of processed food, as evidenced from the change in competitive position in the Trade Performance Index for Kenya, Malawi, Ghana and Mozambique. Importers in Africa Low-income countries are also focusing on international business development. Despite being landlocked and among the group of least developed countries (LDCs), Ethiopia has become a competitive international supplier of several products and services. Ethiopian producers are now a leading source for sesame seeds, with an 11% share of world imports. Ethiopia's coffee export values and quantities have expanded at double-digit rates between 2013 and 2018, earning well over US$ 375 million in 2018. Ethiopian transport companies, including Ethiopian Airlines, chalked up export earnings from transport services of US$ 180 million in 1998. Finding Importers in Africa The Africa Business Pages has compiled the Africa Business Directory to help global exporters connect with importers in Africa for direct B2B interaction. Segmented by countries as well as business secretors, the Africa Business Directory has helped many exporters connect with their business counterparts in African countries. In addition to specific country directories, you can also download sector specific directories for the following business sectors: Africa Automotive Directory Africa Tyre Dealers Directory Africa Building & Construction Directory Africa Cosmetics & Beauty Directory Africa Foodstuff Directory Africa Health & Medical Directory Africa Hotels & Restaurants Directory Africa Pharmaceuticals Directory Africa Hospitals Directory Africa Rice Importers Directory Africa Furniture Directory Africa Security Directory Africa Car Importers Directory By contacting importers in Africa using the Africa Business Directories, you can take the first step towards increasing your exports to Africa and finding the right business partners for your business.
Cryptocurrency: The Start of an African Economic Renaissance
folder_open Articles , Business Outlook
Cryptocurrencies and blockchain assets are the newest and potentially most promising new asset class. Cryptocurrencies are gradually being discovered in Africa. In countries like South Africa, Ghana, Kenya, Botswana, Zimbabwe and Nigeria, there is a semblance of digital currencies, primarily bitcoin, taking roots. Blockchain or DLT (Distributed Ledger Technology) can be seen as the solution for Africa’s current problems and future growth. Bitcoin, based on blockchain, could be the engine for African growth, and could fuel the continent's great leap forward. Cryptocurrencies are classified as a subset of digital currencies and are also classified as a subset of alternative currencies and virtual currencies. Bitcoin became the first decentralized cryptocurrency in 2009. Blockchain is another important concept that needs to be defined. As such, blockchain is a continuously growing list of records, called blocks, which are linked and secured using cryptography. Investment returns in cryptocurrencies in recent times have by far outperformed traditional assets such as global stocks and bonds. However, public opinion and investors’ minds on cryptocurrencies are divided and it often comes down to a philosophical and even emotional debate. This is also true about African policymakers and their official stance on cryptocurrency. High volatility and unexplained falls, risks of hacking attacks and ransom with the subsequent sensational media headlines are reasons why many investors still shy away from cryptocurrencies and merely think of it as “magical internet money.” The biggest fallacy many casual observers and some government officials have, is that they say they like blockchain, but they do not like cryptocurrencies like Bitcoin, Ether and Litecoin, etc. That argument is the same as people in 1994, before the introduction of the Internet web browser, arguing that they do not like the public censor-free Internet (it is not regulated and not “owned” by anybody etc.), but rather have a privately controlled intra-net. A private blockchain without a trustless and distributed consensus-based crypto-currency is nothing more than a shared database or intra-net. Proponents of cryptocurrencies are of the firm belief that blockchain could soon give rise to a new era of the Internet even more disruptive and transformative than the current one. Blockchain's ability to generate unprecedented opportunities to create and trade value in society via cryptocurrencies will lead to a generational shift in the Internet's evolution, from an Internet of Information to a new generation Internet of Value. Any government that embraces cryptocurrencies is going to benefit so much by owning the money that is native to the internet. In a similar fashion, in this case the Internet of money, one can see the disruption potential of cryptocurrencies. Just like the Internet took out Hollywood with Netflix, Spotify took out the music business, and Google and Facebook took out advertising and media businesses, cryptocurrencies will take out the finance industry as we know it. The Case for Cryptocurrencies in Africa There is high potential for Africans to leapfrog some of the existing financial services, in the same way that many Africans skipped the part of owning a cumbersome and expensive landline and went straight to owning a mobile phone. In the “old” or “traditional” system, traditional bankers in suits were the miners of the old generation, getting paid in the currency of the central bank run by un-elected officials. That system is also characterised by fiat currency being mined by the fractional reserve banking system, bank bail-outs and large costs to ordinary tax payers, amid the rise of populism. The new central bankers are the cryptographers. The new owners of the financial infrastructure are the holders of the cryptocurrency coins, which is or could be everybody. While cryptocurrency has been hailed for its potential in the financial sector of the developed world, one of its greatest applications has been virtually overlooked. In nations that lack dependable economic systems or governance, digital currency may offer hope. Access to finances, security and privacy of funds, and faith in a common medium of exchange, can aid many across the African continent. Several African countries have exchanges and start-ups in the crypto space, and their businesses are recognizing the significance of cryptocurrencies in fostering cross-border trade and payment. Moreover, the infrastructure for the take-off of digital tokens is solid. Telecommunication liberalisation across the continent has enabled Internet accessibility remarkably. Figures from GSMA indicate that half of Africa’s population is subscribed to mobile telephony. Also, the statistics indicate that for the past two years, smartphone usage in the continent has doubled to reach 226 million. The new finance industry will settle on where the innovation will be for smart contracts and cryptocurrencies. It is Silicon Valley’s replacement for the old infrastructure of finance and Africa’s chance to leapfrog the old system. It will position the economies of Africa for the future of finance. With Africa not having a strong legacy system in place, as is the case with the developed world, is suddenly a great advantage. Still, too many adult people in Africa do not have access to bank accounts. This wretched situation denies countless numbers of people financial freedom. Bureaucratic tenors and economic exclusion, amongst others, have paved the way for this situation. A recent study of 10 African nations with unusual inflationary ratios, indicated that South Sudan had a huge inflation rate of 295%. Egypt had the lowest rate with 12.30%. High inflation and weak African currencies allow Bitcoin and cryptocurrencies to offer African consumers a stable store of value and an inflation hedge. African nations have lagged in traditional banking, but the phenomenal success of Kenya’s Safaricom M-Pesa shows that this is and can be an advantage in the coming blockchain economy. Safaricom’s success has shown that Microsoft Founder Bill Gates’ adage of “Banking as a function is necessary, Banks are NOT”, holds very true. What Safaricom’s M-Pesa achieved on a country scale, cryptocurrency can achieve on a pan-African scale. Cryptocurrency remittance services in Africa have sprung up as an alternative to Western Union, and international organizations have employed blockchain technology to assist refugees. Still, it appears that many of the communities most desperate for this innovation have yet to embrace the monetary haven. Africa’s wide adoption of crypto-currency would further progress themove to the democratization of financial services. Kazakhstan became the second country in the world, after Japan, to recognize the need for the development of the cryptocurrency market system at governmental level. The development of the digital currency market, based on the Astana International Financial Centre, is the first step towards the creation of a fully-fledged ecosystem for the digital economy. Forward-looking governments in Africa should try to emulate the developments in Japan and Kazakhstan. Practices and Challenges of Cryptocurrency in Africa Large scale adoption in Africa, however, is still slow. Awareness, education and user experience are some reasons why the take-up is taking time. Switzerland and Singapore are both successful countries with strong currencies, and as such have nothing to lose by embracing fintech and cryptocurrency. Countries with high inflation and currency controls in place seem to be paranoid about the rise of cryptocurrency. However, similar to the Internet, it is difficult to ban and/or control. In recent times, the African market has seen the emergence of more than 10 Bitcoin exchanges seeking to provide cheap and efficient trading services to African consumers. Some exchanges have expanded their services and have established an office in Africa to serve the new market and observe the demand of Bitcoin in several African countries. In East Africa, local innovators have introduced cryptocurrency systems to support cross-border transactions, as exemplified by initiatives like BitPesa. In South Africa, cryptocurrencies are becoming particularly popular. In Nigeria, local traders and activists believe this new money presents an opportunity to democratize the economy. This is propelled by the fact that people in Nigeria have been failed by conventional money. The Central Bank of Nigeria, which oversees an inflation rate of 14%, making it the 6th highest inflation rate in the world, recently announced that they cannot stop Bitcoin. Their statement read: “Central bank cannot control or regulate bitcoin. Central bank cannot control or regulate blockchain. Just the same way no one is going to control or regulate the Internet. We don’t own it.” This is very sensible and the correct and forward-looking approach. While several exchanges offer conventional payment methods, such as bank transfers and account top-ups, a few platforms, like BTCGhana, provide local users and the underbanked population simpler methods of purchasing and selling Bitcoin. On the BTCGhana platform, users can make Bitcoin purchases through established exchange platforms and can, within minutes, send the payment to local remittance platforms, including TigoCash, Airtel Money and MTN Mobile Money. This service allows African users to pick up cash at local remittance outlets with ease, without having to deal with complex withdrawal and deposit methods The African market has seen the emergence of more than 10 Bitcoin exchanges seeking to provide cheap and efficient trading services to African consumers. Conclusion Africa has lots to offer Bitcoin and other cryptocurrencies, simply because Africa needs an alternative to the weak and not–always–available nor reliable local African fiat money. All products of cryptocurrencies will be well-embraced if promoted in Africa. The current vacuum for alternative means of payment in Africa is obvious. Cryptocurrency is not just a solution to the plight of the “unbanked.” Rather, it is a method for allowing economically or politically subjugated populations to control their own wealth. Non-fiat digital currency can bring millions of people into a secure and person-driven global economy. The intangible nature of digital currencies means that a government cannot physically remove the wealth of a citizen. This paradigm shift is a monumental step forward in the social contract, providing an additional layer of security to individuals. All populations, especially those that are disadvantaged, need a way to maintain access to their wealth from anywhere in the world. Imagine if a refugee could access a bank account even after being displaced from their home country. This could help maintain the refugee’s dignity and hopefully diminish the extreme poverty caused by this terrible upheaval. This is the unrealized potential of virtual currency. In a nation where political activists are jailed, or inflation runs rampant, a non-fiat virtual currency may offer an escape. Cryptocurrency is humanity’s greatest iteration on the aphorism that there is strength in numbers. For many, a virtual currency could become the next step in the social contract – a world that lives, breathes, and functions outside the boundaries of a government. For the first time, open minded early adopters can make a Silicon Valley venture capital style bet on the future of money and finance and the development of African economies Like any other investments, cryptocurrencies carry risks. However, not owning or embracing the native money of the Internet is even riskier. Cryptocurrency is a fast-evolving, complex phenomenon that in my view will have a major impact on power distribution in the global economy and on the African continent. The intangible nature of digital currencies means that a govern-ment cannot physically remove the wealth of a citizen. This para-digm shift is a monumental step forward in the social contract, providing an addi-tional layer of security to indivi-duals.
Preliminary request for participation in the trade show
place
calendar_today
Preliminary request for visitor registration
Visitor Registration
place
calendar_today